Airbnb Occupancy Rates in Salford, Greater Manchester(October 2026)
MediaCity studios, Salford Quays cranes, and Metrolink trams shape how guests picture Salford before they book. The borough sits west of Manchester city centre with its own council, waterfront towers, and university quarter.
As of October 2026, Salford averages £23,475 annual revenue per listing with 54% occupancy and £119 ADR across 893 active listings. Quays and Ordsall hold waterfront flats for MediaCity contractors and arena spillover. Pendleton & Charlestown and Claremont serve university parents and hospital visitors. Eccles and Boothstown & Ellenbrook terraces pull families who want parking within a short tram ride of Deansgate.
Underwrite the ward first. A Quays high-rise with a balcony view and an Eccles semi with a driveway are different products even when both sit inside the Salford average.
Salford Airbnb Market Map (October 2026)
Salford Market Performance
England average: 59% occupancy, £168 per night.
Airbnb occupancy rates by city in EnglandPeriod: October 2025 - September 2026
Is Airbnb a Good Investment in Salford?
YES. Salford suits hosts who want Greater Manchester demand with MediaCity and Quays calendars at often lower entry than Manchester city-centre postcodes, provided you confirm planning with Salford City Council and buy stock that matches the guest you can serve.
Salford works when you treat the borough as a peer to Manchester, not a cheaper suffix on a Manchester listing title.
- Salford£23,475 revenue, 54% occupancy, 893 listings: waterfront towers, university mid-weeks, and inner-urban terraces west of the Irwell.
- Manchester£27,587 on 1,963 listings: Piccadilly, Northern Quarter, and arena density at national scale.
- Trafford£23,973 on 406 listings: Old Trafford match weekends and suburban houses with driveways.
- Greater Manchester£25,156 region average on 4,433 listings: ten boroughs with separate planning authorities.
| Market | Avg revenue | Occupancy |
|---|---|---|
| Salford | £23,475 | 54% |
| Manchester | £27,587 | 54% |
| Trafford | £23,973 | 54% |
| Stockport | £22,891 | 55% |
Who tends to invest well
- Hosts buying Quays or Ordsall flats within walking distance of MediaCityUK for Monday–Thursday production crews and weekend waterfront leisure.
- Operators with Pendleton & Charlestown or Weaste & Seedley terraces who can compete on parking, heating, and honest tram times to Deansgate.
Stronger fit elsewhere
- Manchester for pure city-centre arena and Northern Quarter density when lease rules allow.
- Trafford for match-day houses with suburban parking west of the Quays.
- Bolton for lower entry terraces when guests accept a longer Metrolink or rail commute into Manchester.
Synthesis: pick Salford for Quays and MediaCity calendars, university-linked mid-weeks, and inner-urban stock that prices below Manchester towers. Compare Trafford before you assume a Salford postcode captures Old Trafford footfall.
Get Live Salford Market Intelligence
Discover detailed Salford Airbnb Analytics and explore real-time market data to make accurate investment decisions.
Explore Real-time Analytics
How Often Will Your Airbnb Be Booked in Salford?
View Demand Patterns →Occupancy rates directly impact your revenue potential. Understanding demand patterns helps you set realistic expectations and optimize your availability strategy.
The current average occupancy rate in Salford is 54%, meaning properties are booked for about 197 nights per year. However, occupancy varies significantly based on property quality and management. Here's what you can expect:
Airbnb Occupancy Tiers in Salford
Premium(Top 10%) | High-performing(Top 25%) | Average(Median) | Low-performing(Bottom 25%) |
|---|---|---|---|
| 93% | 72% | 45% | 8% |
*High desirability & optimized availability | *Good market fit & guest satisfaction | *Standard market performance | *Higher vacancy, optimization needed |
Seasonal Occupancy Patterns in Salford
October, August
Highest demand and occupancy rates. Perfect for premium pricing strategies and maximizing revenue. Consider longer minimum stays and higher rates.
April, December
Moderate demand with balanced pricing opportunities. Good for attracting budget-conscious travelers while maintaining reasonable occupancy rates.
January, March
Lower demand requires competitive pricing and creative marketing. Focus on local events, extended stay discounts, and targeting specific traveler segments.
How Much Can You Earn with Airbnb in Salford?
Calculate Earnings →One of the most common questions for potential Airbnb hosts in Salford is about earning potential. Let's break down the revenue patterns and what you can realistically expect to earn.
Monthly Revenue Trends in Salford
Best-in-class Airbnb properties (top 10%) in Salford achieve around £32,882 annually, while strong performers (top 25%) earn at least £22,694. Typical properties generate about £11,733 per year, and entry-level listings (bottom 25%) see earnings near £2,155, often with room for optimization. Keep in mind, these are market averages—your actual earnings can be even higher depending on your property's location, bedrooms, guest capacity, and unique amenities.
Want to see how your listing could perform? Create a free account to unlock personalized analytics and explore exclusive insights in our app!
What Can You Learn from Top-Performing Airbnbs in Salford?
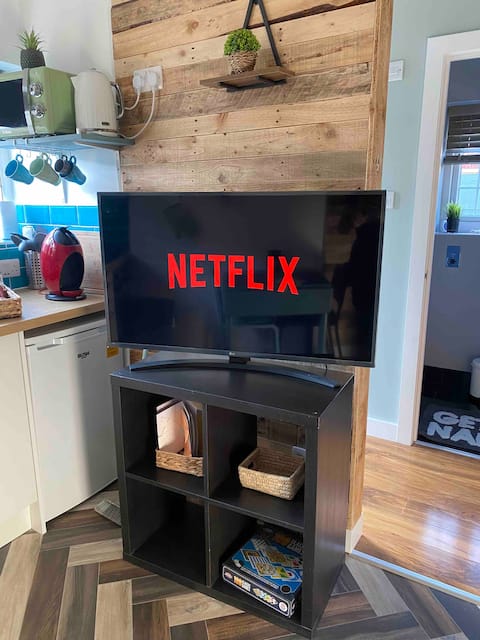
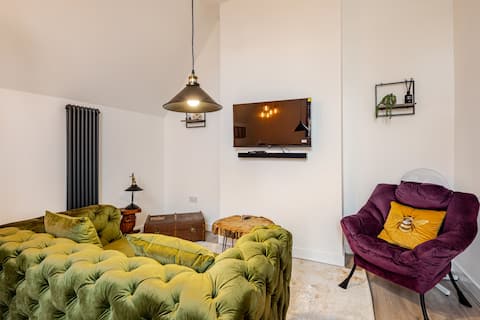
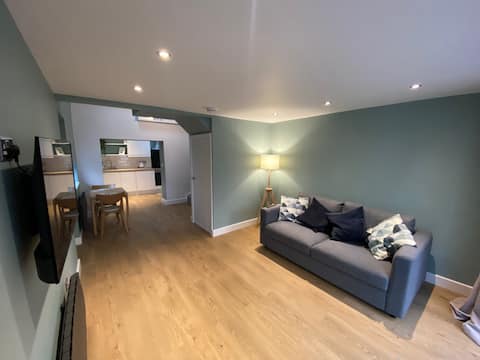
View Top Performers →Studying successful properties provides valuable insights for your own Airbnb strategy. Here are the top-performing listings in Salford and what makes them successful.
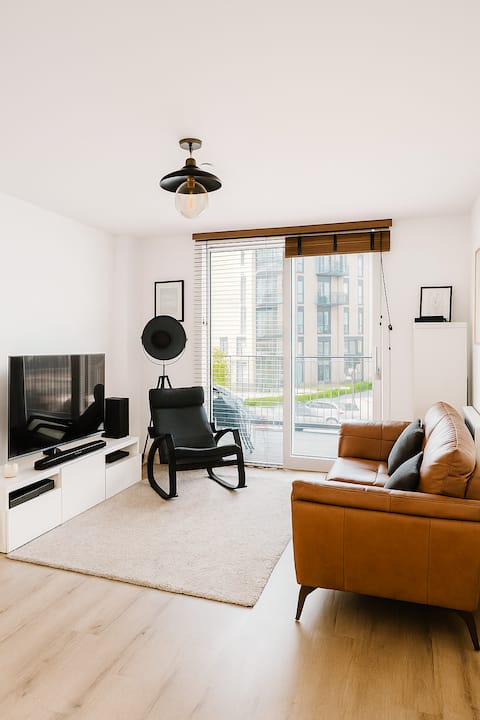
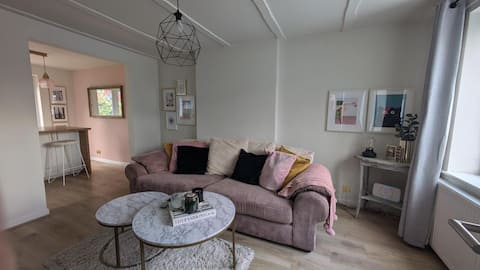
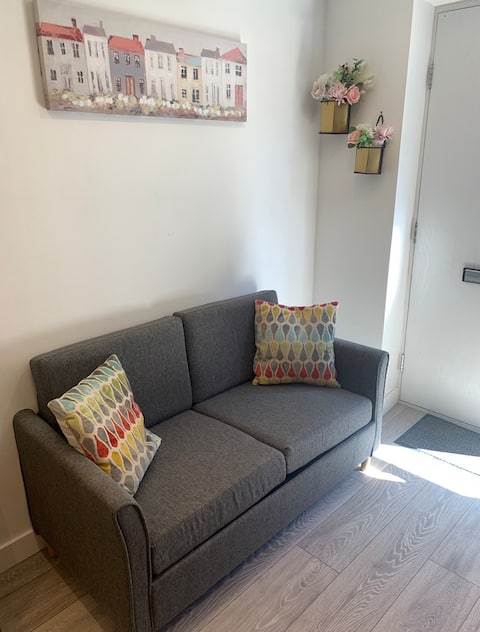
Salford Market Analysis
MediaCity, Quays towers, and arena spillover
Salford’s highest-profile demand clusters around MediaCityUK, the Lowry, and Imperial War Museum North on the Quays waterfront. Production schedules, BBC and ITV contractor blocks, and conference guests into Manchester Central fill Quays (132 listings) and Ordsall (183 listings) when listings publish balcony photos, honest walking times to MediaCity, and minimum-night rules for busy production weeks. Weekend leisure guests book the same flats for waterfront dining and tram hops into Deansgate, so hosts who split corporate and leisure pricing outperform hosts who leave one rate on all year.
The rest of the calendar still matters. Blackfriars & Trinity and Broughton absorb hospital visitors, university open days, and short creative contracts Monday–Thursday. Winter occupancy holds when the listing offers fast Wi-Fi, reliable heating in converted mills, and clear Metrolink times when evening events run late at the AO Arena across the river.
University of Salford, hospitals, and inner-urban terraces
Pendleton & Charlestown (73 listings), Claremont (36 listings), and Weaste & Seedley (72 listings) trade slightly lower weekend ADR than Quays towers for steadier mid-week stays linked to the University of Salford, Salford Royal, and Pendleton campus blocks. Kersal & Broughton Park (24 listings) adds leafy Victorian streets for guests who want quieter bedrooms with a short bus to the centre. Price those corridors on occupancy consistency, not only peak nightly rates on Quays balconies.
Eccles, Boothstown, and the western commuter belt
Eccles (53 listings), Boothstown & Ellenbrook (6 listings), and Worsley & Westwood Park (8 listings) serve families and longer mid-stays who want driveways, canal walks, and Metrolink links into Manchester without paying Deansgate tower prices. Cadishead & Lower Irlam and Higher Irlam & Peel Green sit on the south-west fringe with more parking and lower nightly rates than the Quays core. Minimum-night flexibility helps when guests book school-holiday weeks that combine MediaCity day trips with suburban evening quiet.
What Are the Airbnb Regulations in Salford?
Understanding local regulations is crucial for operating a successful Airbnb. Let's examine the compliance landscape and what you need to know about licensing requirements in Salford.
Registration Numbers on Airbnb
None of the active Airbnb listings we tracked last month display a registration or license number.
This reflects what hosts publish on their Airbnb listings, not the local legal requirements. Always confirm them with local authorities.
Do I need planning permission to let my whole home in Salford?
Whole-property short-term letting can count as a material change of use under national planning rules. Salford City Council assesses each address through its planning service. Article 4 directions and ward-level policies can remove permitted development rights, so check the property’s planning history before you list.
Is there a Salford Airbnb licence?
Salford does not issue a separate tourist short-stay licence like some European cities. Compliance is planning (change of use where required), lease and mortgage consent, tax, safety certificates, and national registration duties. Many Quays and city-fringe leases ban sub-letting even when planning is clear.
What about business rates and the national register?
Self-catering stock available 140+ days a year and actually let 70+ days may move onto business rates. Track GOV.UK self-catering rules and the forthcoming short-term let registration scheme. England has no automatic 90-night cap outside Greater London; permission depends on how the home is used in practice.
Council Tax, HMO rules, and safety
Confirm current Council Tax bands and any second-home premiums on Salford City Council’s Council Tax pages. HMO licensing and selective licensing schemes target longer-term private renting and are separate from tourist letting, but shared houses used for short stays may still trigger HMO standards. Confirm fire, gas, electrical, and EPC compliance for paying guests, and declare rental income to HMRC before the first booking.
What Should You Charge for Your Airbnb in Salford?
Smart Pricing Tools →Pricing is one of the most critical decisions for Airbnb success. Let's analyze the current pricing landscape and help you understand what rates you can realistically charge.
The current average daily rate in Salford is £119 per night. However, pricing varies significantly based on property quality and location. Here's what different property tiers typically charge:
Airbnb Pricing Tiers in Salford
Premium(Top 10%) | High-performing(Top 25%) | Average(Median) | Budget(Bottom 25%) |
|---|---|---|---|
| £164per night | £128per night | £99per night | £53per night |
*Top locations, big properties, premium amenities | *Good property management, highly rated | *Standard market performance | *Basic properties, less desirable locations |
Is It Profitable to Start an Airbnb in Salford?
Investment Analysis →Understanding the profitability potential is crucial for any Airbnb investment decision. Let's analyze the revenue performance and profit margins in the Salford market to help you make informed financial decisions.
Revenue Performance
Profitability Factors
Which Areas in Salford Are Most Profitable for Airbnb?
Explore All Areas →Salford’s 893 listings spread across 20 electoral wards. The borough average of £23,475 blends Quays high-rises, inner terraces, and western suburban houses. Rank the wards below by inventory depth first, then compare occupancy and nightly rates on each ward page as stats refresh after the polygon export.
### Top Performing Neighborhoods
Quays: 132 listings averaging £22,332 at 54% occupancy. Waterfront towers, the Lowry, and MediaCity footfall concentrate here. Parking is scarce; honest resident-zone notes and tram times outperform generic “Manchester city centre” titles.
Ordsall: 183 listings at £25,249 with 61% occupancy. Victorian terraces and new-build flats between MediaCity and the Irwell. Production mid-weeks and arena spillover weekends when Wi-Fi and heating are baseline.
Pendleton & Charlestown: 73 listings earning £18,707 at 50% occupancy. University of Salford parents, hospital visitors, and Pendleton campus blocks. Two-bedroom terraces with parking convert better than studio-only stock far from Metrolink.
Claremont: 36 listings at £24,100. Inner-urban streets with bus links toward the Quays and Manchester. Slightly lower entry than waterfront towers with steadier mid-week occupancy.
Weaste & Seedley: 72 listings at £23,565 with 50% occupancy. Terraces south of the university with parking and tram access toward Eccles and the city.
Quays & MediaCity waterfront
Quays and Ordsall are the waterfront product. Guests pay for balcony views, museum weekends, and short walks to MediaCity sets. High-rise leases often restrict sub-letting, so verify management rules before exchange. Listings that explain visitor parking, lift access, and rainy-day walking routes to the tram convert better than listings that promise “free parking” without detail. Corporate mid-week blocks fill these wards when reviews mention desk space and reliable heating through winter.
### Inner Salford & Broughton corridors
Blackfriars & Trinity (147 listings), Broughton (68 listings), and Kersal & Broughton Park (24 listings, £17,724 revenue) serve guests who want lower entry prices with bus or tram links toward Deansgate. Pendlebury & Clifton (13 listings) and Little Hulton (6 listings) add northern residential belts with more parking and family-oriented calendars.
### Eccles, Swinton, and Walkden
Eccles (53 listings, £17,327 revenue), Swinton & Wardley (10 listings), Swinton Park (11 listings), and Walkden North / Walkden South cover the western and north-western commute belt. Families book driveways, canal towpaths, and Metrolink times into Manchester. Barton & Winton (21 listings) and Boothstown & Ellenbrook sit on the affluent western edge with larger houses and longer leisure stays.
### Greater Manchester peers
Hosts comparing Salford should also read Manchester (1,963 listings, £27,587 revenue), Trafford (406 listings), and the Greater Manchester region page before fixing on a Quays postcode alone.
Explore Other Markets in England
Airbnb Occupancy Rates in Queen's Park, Greater London
City Of Westminster, England
9,781 Active Listings
Airbnb Occupancy Rates in Windermere And Bowness, Cumbria
Westmorland And Furness, England
858 Active Listings