Airbnb Occupancy Rates in Liverpool, Merseyside(October 2026)
Albert Dock warehouses, Lime Street arrivals, and Anfield match weekends set Liverpool’s short-stay rhythm. Beatles tourism, ACC Liverpool conferences, and university open days keep the same streets busy between fixtures.
As of October 2026, the city averages £25,838 annual revenue per listing, 48% occupancy, and £148 ADR across 2,357 active listings. Central and Riverside hold most of that inventory. Anfield and Everton spike on home calendars. Greenbank and Wavertree serve quieter two-night stays with parking.
Underwrite the ward, then the building. A dock-adjacent warehouse conversion and a Wavertree terrace are different products even when both sit inside the Liverpool average.
Liverpool Airbnb Market Map (October 2026)
Liverpool Market Performance
England average: 59% occupancy, £168 per night.
Airbnb occupancy rates by city in EnglandPeriod: October 2025 - September 2026
Is Airbnb a Good Investment in Liverpool?
YES. Liverpool suits hosts who want a large English city calendar built on waterfront tourism, football weekends, and mid-week conferences, provided you confirm planning with Liverpool City Council and pick a ward that matches the guest you can actually serve.
Liverpool works best if:
- You can walk guests to the Albert Dock, Lime Street, or a home ground without a long taxi disclaimer.
- You have already checked lease, freeholder, and mortgage rules on the exact flat, because many riverside blocks restrict sub-letting.
- You are ready to price match weekends separately from ACC conference mid-weeks and university open days.
- You have compared Sefton and Wirral on the Merseyside landing before assuming every guest wants a city-centre postcode.
Manchester offers denser arena and corporate mid-weeks at national event scale. Birmingham is the Midlands peer with exhibition-led demand. Liverpool’s edge is the combination of UNESCO waterfront sightseeing, two Premier League calendars, and rail access from London and Manchester on the same trip.
| Market | Avg revenue | Occupancy | Listings |
|---|---|---|---|
| Liverpool | £25,838 | 48% | 2,357 |
| Merseyside | £25,734 | 49% | 3,346 |
| Sefton | £26,461 | 51% | 425 |
| Wirral | £26,881 | 54% | 404 |
| Manchester | £27,587 | 54% | 1,963 |
Confirm planning on Liverpool City Council’s planning pages before you list. England has no automatic 90-night cap outside Greater London; permission is about material change of use, and many apartment leases are stricter than the council.
Who tends to invest well
- Hosts buying Central or Riverside flats within walking distance of the docks, the museums, and Lime Street for weekend city breaks plus Monday–Thursday conference stays.
- Operators who can staff Anfield and Everton houses on fixture weekends and still fill mid-weeks with contractors.
Stronger fit elsewhere
- Sefton for Aintree, Formby, and Southport coast calendars with suburban parking.
- Wirral for peninsula houses and ferry-access stays facing the city skyline.
- Manchester for national arena and exhibition density at £27,587 average revenue.
Get Live Liverpool Market Intelligence
Discover detailed Liverpool Airbnb Analytics and explore real-time market data to make accurate investment decisions.
Explore Real-time Analytics
How Often Will Your Airbnb Be Booked in Liverpool?
View Demand Patterns →Occupancy rates directly impact your revenue potential. Understanding demand patterns helps you set realistic expectations and optimize your availability strategy.
The current average occupancy rate in Liverpool is 48%, meaning properties are booked for about 175 nights per year. However, occupancy varies significantly based on property quality and management. Here's what you can expect:
Airbnb Occupancy Tiers in Liverpool
Premium(Top 10%) | High-performing(Top 25%) | Average(Median) | Low-performing(Bottom 25%) |
|---|---|---|---|
| 85% | 65% | 41% | 16% |
*High desirability & optimized availability | *Good market fit & guest satisfaction | *Standard market performance | *Higher vacancy, optimization needed |
Seasonal Occupancy Patterns in Liverpool
September, July
Highest demand and occupancy rates. Perfect for premium pricing strategies and maximizing revenue. Consider longer minimum stays and higher rates.
December, April
Moderate demand with balanced pricing opportunities. Good for attracting budget-conscious travelers while maintaining reasonable occupancy rates.
January, February
Lower demand requires competitive pricing and creative marketing. Focus on local events, extended stay discounts, and targeting specific traveler segments.
How Much Can You Earn with Airbnb in Liverpool?
Calculate Earnings →One of the most common questions for potential Airbnb hosts in Liverpool is about earning potential. Let's break down the revenue patterns and what you can realistically expect to earn.
Monthly Revenue Trends in Liverpool
Best-in-class Airbnb properties (top 10%) in Liverpool achieve around £39,500 annually, while strong performers (top 25%) earn at least £24,917. Typical properties generate about £13,825 per year, and entry-level listings (bottom 25%) see earnings near £4,833, often with room for optimization. Keep in mind, these are market averages—your actual earnings can be even higher depending on your property's location, bedrooms, guest capacity, and unique amenities.
Want to see how your listing could perform? Create a free account to unlock personalized analytics and explore exclusive insights in our app!
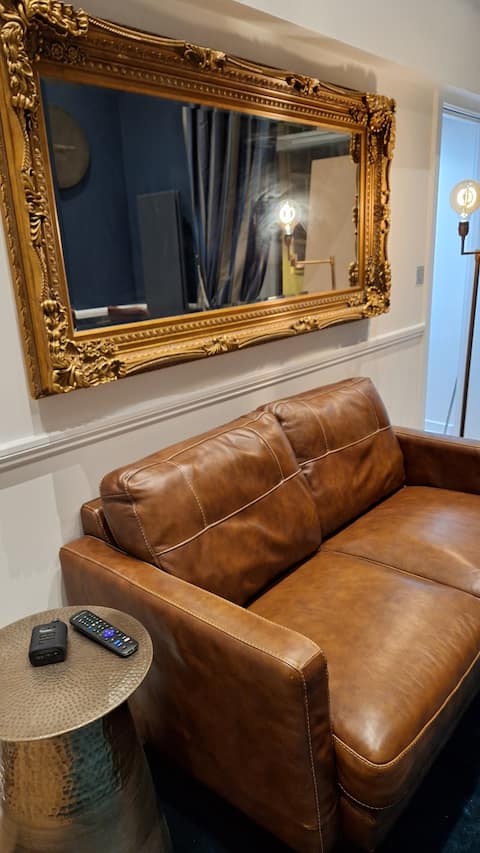
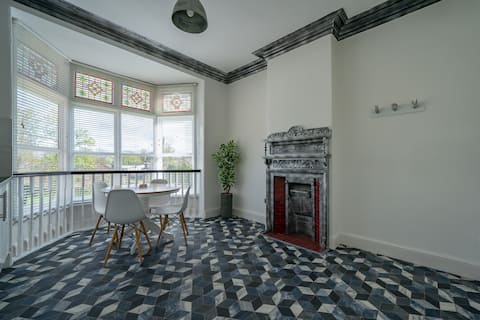
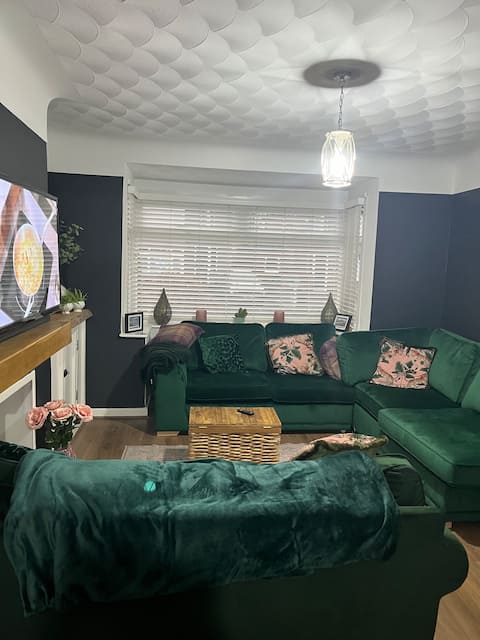
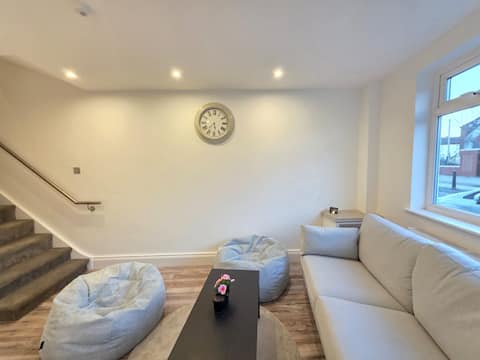
What Can You Learn from Top-Performing Airbnbs in Liverpool?
View Top Performers →Studying successful properties provides valuable insights for your own Airbnb strategy. Here are the top-performing listings in Liverpool and what makes them successful.
Liverpool Market Analysis
How Liverpool’s calendar actually fills
Most of the 2,357 listings sit in a handful of inner wards. Central (669 listings) and Riverside (479 listings) absorb Beatles tourism, cruise-day overflow from the landing stage, and ACC Liverpool delegates who want a warehouse conversion with a lift. Nightly rates (ADR) hold when the listing shows a real walking time to the Albert Dock and an honest note about Saturday noise.
North of the core, Kirkdale, Anfield, and Everton run a football calendar. Home weekends fill two- and three-bedroom houses with parking. Those same streets need a mid-week story (contractors, hospital visitors, university parents) or occupancy falls between fixtures. Princes Park and Kensington and Fairfield sit between the Georgian parks and the inner east, with more space than a Central studio and a shorter walk to the stations than Wavertree.
Festival weeks and football winters
Spring and early summer bring waterfront sightseeing, graduation weekends, and the first run of concert dates at the city’s indoor arenas. Late summer stays busy on the docks while suburban wards such as Greenbank and Wavertree pick up families who want a terrace, a park, and a driveway. Autumn and winter lean on the Premier League calendar, Christmas markets around the waterfront, and conference mid-weeks. Price those seasons as separate products. A Riverside one-bed that sells out on a European home tie will not automatically fill a wet Tuesday in February without workspace, fast Wi-Fi, and invoice-ready hosting.
- Walk the route from the front door to Lime Street, the Albert Dock, or the relevant stadium and put that time in the listing title.
- Split your calendar: match weekends, ACC conference blocks, and university open days need their own minimum-night and cleaning rules.
- Confirm planning with Liverpool City Council and lease consent on the exact plot, especially in converted dock warehouses.
- Check Council Tax on second homes if the unit will sit empty between lets.
- Compare Sefton and Wirral if your guest needs parking and a quieter night more than a dock view.
- Read GOV.UK self-catering rules for the 140-available / 70-let business-rates test and the forthcoming national register.
- Keep fire, gas, electrical, and EPC certificates current. Review scores in this market move occupancy as much as headline ADR.
What Are the Airbnb Regulations in Liverpool?
Understanding local regulations is crucial for operating a successful Airbnb. Let's examine the compliance landscape and what you need to know about licensing requirements in Liverpool.
Registration Numbers on Airbnb
None of the active Airbnb listings we tracked last month display a registration or license number.
This reflects what hosts publish on their Airbnb listings, not the local legal requirements. Always confirm them with local authorities.
| Requirement | Where to file | Link |
|---|---|---|
| Planning / change of use | Liverpool City Council | Planning and building control |
| When permission is needed | England PPG | When is permission required? |
| Holiday-let rules (rates, safety, tax) | GOV.UK | Self-catering holiday home in England |
| National short-term let register | GOV.UK (scheme not yet live) | Registration scheme guidance |
| Second-home Council Tax | Liverpool City Council | Empty properties and second homes |
| Income tax on lets | HMRC | Rental income |
Liverpool City Council does not run a separate Airbnb licence. Whole-property letting is assessed as planning (material change of use) plus national tax, rates, and safety rules. Outside Greater London there is no automatic 90-night cap; permission depends on how the home is used in practice. Many dock and city-centre leases ban sub-letting even when planning is clear, so read the deeds before exchange.
Self-catering stock available 140+ days a year and actually let 70+ days may move onto business rates. Track the national register, which is confirmed in law but not yet a live portal. Liverpool charges 200% Council Tax on second homes, with holiday-use exceptions listed on the council page above. HMO Article 4 and selective licensing in the city apply to longer-term private renting; do not treat those schemes as a tourist licence. Confirm fire, gas, electrical, and EPC standards for paying guests before the first booking.
What Should You Charge for Your Airbnb in Liverpool?
Smart Pricing Tools →Pricing is one of the most critical decisions for Airbnb success. Let's analyze the current pricing landscape and help you understand what rates you can realistically charge.
The current average daily rate in Liverpool is £148 per night. However, pricing varies significantly based on property quality and location. Here's what different property tiers typically charge:
Airbnb Pricing Tiers in Liverpool
Premium(Top 10%) | High-performing(Top 25%) | Average(Median) | Budget(Bottom 25%) |
|---|---|---|---|
| £249per night | £157per night | £105per night | £69per night |
*Top locations, big properties, premium amenities | *Good property management, highly rated | *Standard market performance | *Basic properties, less desirable locations |
Is It Profitable to Start an Airbnb in Liverpool?
Investment Analysis →Understanding the profitability potential is crucial for any Airbnb investment decision. Let's analyze the revenue performance and profit margins in the Liverpool market to help you make informed financial decisions.
Revenue Performance
Profitability Factors
Which Areas in Liverpool Are Most Profitable for Airbnb?
Explore All Areas →Liverpool’s 2,357 listings spread across 30 electoral wards. The city average of £25,838 blends a dense waterfront core with quieter southern terraces. Rank the wards below by inventory first, then compare occupancy and nightly rates on each ward page.
Top Performing Neighborhoods
Central: 669 listings averaging £28,274 at 46% occupancy. Lime Street, the Knowledge Quarter, and walkable bars concentrate here. Lift access and a stated walking time to the station outperform generic “city centre” titles.
Riverside: 479 listings at £29,144 with 53% occupancy. Albert Dock, the museums, and the waterfront arena pull weekend sightseeing and conference overflow into warehouse conversions.
Kirkdale: 182 listings earning £18,378 at 46% occupancy. North-end houses with parking serve match weekends and contractor mid-weeks along the northern approach to the centre.
Anfield: 170 listings at £23,729 and 41% occupancy. Home fixtures fill three-bedroom stock. Hosts who publish the club calendar and a clear bag-drop plan convert better than hosts who only mention “near the stadium”.
Princes Park: 103 listings averaging £39,831. Georgian streets and the park draw longer leisure stays who want more space than a Central studio.
Kensington and Fairfield: 101 listings at £21,760. Inner-east terraces with a shorter hop to Lime Street than the southern suburbs, often at a lower entry price than Riverside warehouses.
Waterfront and dock warehouses
Riverside and the western edge of Central are the sightseeing product: UNESCO waterfront, museums, and cruise-day footfall. Converted warehouses with lifts, reliable heating, and blackout blinds hold reviews through winter when dock winds pick up. Allocated parking is scarce, so listings that tell the truth about NCP or resident-permit streets waste fewer first nights. Conference guests from ACC Liverpool book these same buildings Monday–Thursday when the listing offers a desk and invoice-ready hosting.
Match-day north
Anfield, Everton (92 listings, £18,929 revenue), Kirkdale, and County (63 listings) sit on the northern football belt. Two- and three-bedroom houses with a driveway outperform compact flats on fixture weekends. The operational job is filling the gaps: hospital visitors, university parents, and contractors keep occupancy up when both clubs play away. Tuebrook and Stoneycroft (80 listings) adds inner-east inventory on the same northern approach.
Parks, universities, and the southern terraces
Greenbank (54 listings), Wavertree (28 listings), St Michael’s (64 listings), Picton (38 listings), and Old Swan (49 listings) serve guests who want a park, a terrace, and a supermarket within a short walk. University of Liverpool and LJMU open days, plus family city breaks, fill these wards when the listing includes parking notes and an honest bus or train time to Lime Street. They rarely match Riverside’s weekend ADR, and they often post steadier mid-weeks.
Merseyside peers
Hosts comparing the city should also read Sefton (425 listings, £26,461 revenue) for Aintree and the coast, Wirral (404 listings) across the water, St. Helens (97 listings), and the Merseyside region page before fixing on a Liverpool postcode alone.
Explore Other Markets in England
Airbnb Occupancy Rates in Queen's Park, Greater London
City Of Westminster, England
9,781 Active Listings
Airbnb Occupancy Rates in Windermere And Bowness, Cumbria
Westmorland And Furness, England
858 Active Listings